
Skip to content

Second Mortgages & Secured Loans

Keep your existing mortgage and raise £5,000 - £500,000.
Most legal purposes including:

  • Debt consolidation
  • Home improvements
  • School fees

THINK CAREFULLY BEFORE SECURING DEBTS AGAINST YOUR HOME. YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE OR ANY OTHER DEBT SECURED ON IT.

AN ILLUSTRATIVE EXAMPLE

Explore your repayments

See what your monthly repayments could look like. Adjust the amount and loan term to explore the options that may suit you.

Term

Illustrative monthly repayment

£606.64

£50,000 over 10 years at
an illustrative rate of 8% annual interest rate

Explore your options

Illustrations only. Borrowing is subject to lender criteria, affordability and individual circumstances. The calculator does not include any fees that may or may not be added to the loan. See section on fees.

FROM AN IDEA TO YOUR NEXT STEP

Let’s make it feel simpler.

A clear process, with real people along the way.

  1. 01

    Complete the short form

    The Get a quote form covers the amount and purpose, the property and mortgage, and how to reach you.

  2. 02

    Loans Warehouse gets in touch

    They receive the enquiry and contact you to gather further information. That conversation is a fact-find.

  3. 03

    Advice, then any application

    If a second charge is suitable, they recommend a lender and product. Paperwork follows only if you want to proceed.

WHAT HAVE YOU GOT IN MIND?

Different plans. A place to start.

Understand the options, the costs and what they could mean for you.

Securing debts against your home puts it at risk. A longer repayment term may lower monthly payments but increase the total amount repaid.

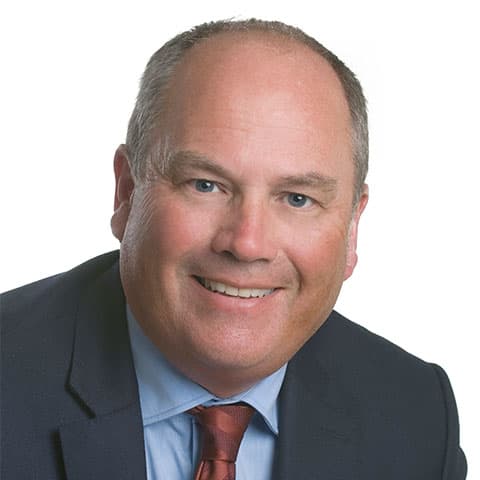
Mark Fry, founder and managing director of The Second Mortgage CompanyMark Fry · Founder

A REAL PERSON BEHIND THE NAME

Finance is personal.
So are we.

Meet Mark Fry, founder of The Second Mortgage Company. He reviews the information on this site. After you send an enquiry, Loans Warehouse contacts you and provides the advice and assessment.

UNDERSTAND BEFORE YOU DECIDE

A little clarity goes a long way.

Explore our guides

What is a second mortgage?

A second mortgage, often called a second charge mortgage or secured loan, is a separate loan secured on a home that already has a first mortgage. It runs alongside the first mortgage rather than replacing it. The first lender is repaid first if the property is sold or repossessed, and both repayments must be maintained.

Read more about second charge mortgages, also known as secured loans or homeowner loans. These are different from a mortgage to buy a second property.

How does a second charge mortgage work?

A second charge mortgage leaves an existing mortgage in place and adds a separate secured loan. A lender assesses the application, including affordability and the property, before taking a charge that ranks behind the first mortgage. The borrower then has two separate secured repayments, and missing either can put the home at risk.

When might people compare a second mortgage with other borrowing?

People commonly compare a second charge mortgage with remortgaging, a further advance from their existing lender or unsecured borrowing. Each can have different costs, terms, eligibility and risks. A second charge can keep an existing mortgage unchanged, but it creates another secured debt; a regulated adviser can assess the available options.

Borrowing routeWhat changes and what to compare
Second charge mortgageKeeps the first mortgage in place. Adds a separate secured debt and a second repayment.
RemortgageReplaces the first mortgage. Compare the new deal and any early repayment charges on the existing mortgage.
Further advanceAdds borrowing with your existing lender. Compare its lending criteria and the rate on the extra funds.
Unsecured loanDoes not take a charge on your home. Compare the term, monthly repayments and affordability requirements.

Swipe to see more columns

No route is automatically better. Compare total cost, fees, repayment term and any risk to your home. Eligibility and terms depend on your circumstances and the lender; a regulated adviser can assess your options.

Read the full comparison of second mortgages and remortgaging, or explore rates and costs.

What needs careful consideration before secured borrowing?

Secured borrowing can put a home at risk if repayments are missed. The interest rate is only one cost: fees, APRC, the repayment term and any early repayment charge can affect the total amount repaid. Consolidating shorter-term debts over a longer secured term can increase total cost even if monthly payments fall.

Read about risks of a second mortgage and borrowing with adverse credit before starting an enquiry.

How does the quote journey start?

The Get a quote form is a short enquiry. It covers the amount and purpose, the property and mortgage, your name, age and address, employment, income and a self-assessed credit view, with email and phone last. The form is sent to Loans Warehouse for assessment, and Loans Warehouse contacts you. Sending the form is not an application, an offer or a guarantee that finance will be available.

HERE TO HELP

A few questions,
answered.

All frequently asked questions
Is a second mortgage the same as a secured loan?

In UK usage, second mortgage, second charge mortgage, secured loan and homeowner loan often describe extra borrowing secured on a home that already has a first mortgage. They are not a mortgage to buy a second property. Exact product features still depend on the lender and the agreement.

Can I keep my existing mortgage?

A second charge is a separate loan, so the first mortgage usually stays in place. That does not mean every lender will offer terms, or that the first lender's consent is automatic. A regulated adviser can explain what a particular product would do to the existing mortgage.

Is a second mortgage regulated?

Second charge mortgages on a home in the UK are generally treated as regulated mortgage contracts. That is why risk warnings, affordability assessment and clear information matter. For an independent overview, see MoneyHelper and the FCA handbook pages linked from this site.

What happens if I miss repayments?

Missing repayments on a loan secured on a home can lead to arrears charges and, ultimately, repossession. Both the first and second charge can put the home at risk. Read the risks page and MoneyHelper guidance if repayments are under pressure.

WHEN YOU’RE READY

Take the next step.
We’ll take it from there.

Start your enquiry. It is sent to Loans Warehouse, who will contact you about what happens next.

Get a quote

An enquiry is not an offer or a lending decision.

ImportantAs a mortgage is secured against your home, your home could be repossessed if you do not keep up the mortgage repayments. Think carefully before securing other debts against your home.

By The Second Mortgage Company editorial team · Reviewed by Mark Fry, CeMAP, CeRER · Last reviewed/updated 12 October 2026